Many prospective business buyers spend countless hours analyzing the company they want to acquire but overlook an equally important reality:
The lender is evaluating the buyer just as carefully as the business.
When applying for SBA financing, lenders are not simply making a loan to a company. They are investing confidence in the individual or team that will be responsible for operating, growing, and ultimately repaying that loan.
A strong borrower profile can significantly improve the likelihood of approval, while a weak or incomplete package can delay or even derail the financing process.
📊 Personal Financial Strength Matters
One of the first things SBA lenders review is the borrower’s personal financial condition.
Lenders typically require:
✔ Personal Financial Statement (SBA Form 413)
✔ Personal tax returns (usually the last three years)
✔ Personal bank statements
✔ Schedule of personal debts and obligations
✔ Government-issued identification
These documents help lenders understand:
- Net worth
• Liquidity position
• Debt obligations
• Creditworthiness
• Financial responsibility
Lenders want to know whether the borrower has demonstrated sound financial management and possesses the resources necessary to navigate the challenges that often accompany business ownership.
💼 Experience Can Be Just as Important as Capital
A common misconception is that financing decisions are based solely on credit scores and financial statements.
In reality, management capability often plays a critical role.
Lenders frequently review:
✔ Professional resumes
✔ Business ownership experience
✔ Industry expertise
✔ Leadership background
✔ Operational management experience
Why?
Because a profitable business can quickly struggle if placed in the hands of an inexperienced operator.
The strongest borrowers demonstrate a clear connection between their previous experience and the business they intend to acquire.
For example:
A construction manager purchasing an electrical contracting company.
A senior executive acquiring a service business.
A renewable energy professional acquiring a solar installation company.
Relevant experience provides lenders with confidence that the buyer can successfully manage the transition and continue operating the business effectively after closing.
🏢 Understanding Ownership Structure
SBA lenders also require a clear understanding of who owns the business and who will be responsible for decision-making.
Typical requirements include:
✔ Ownership structure and percentage ownership
✔ Organizational charts
✔ Current business affiliations
✔ SBA borrower information forms
✔ Background disclosures
This information helps lenders evaluate:
- Management authority
• Ownership control
• Potential conflicts of interest
• Regulatory compliance
• Eligibility under SBA guidelines
Transparency is critical. Incomplete ownership disclosures frequently create underwriting delays and additional lender requests.
🔍 Character and Compliance Matter
SBA lending is not solely about financial performance.
Lenders also evaluate integrity, transparency, and compliance.
Background disclosures are designed to identify potential issues related to:
- Prior bankruptcies
• Litigation history
• Regulatory matters
• Criminal background concerns
• Existing business relationships
Most issues can be addressed when disclosed early and documented properly.
Problems typically arise when information is omitted or discovered later during due diligence.
🎯 The Three Questions Every SBA Lender Is Asking
At the end of the day, lenders are trying to answer three fundamental questions:
- Can this borrower manage the business successfully?
- Can this borrower repay the loan?
- Can this borrower navigate challenges if market conditions change?
The strongest borrowers provide clear, organized documentation that answers all three questions before the lender even asks.
🤝 Preparing for Success
A well-prepared borrower package demonstrates professionalism, credibility, and commitment.
It tells lenders:
✔ I understand the acquisition process.
✔ I have relevant experience.
✔ I have invested my own resources.
✔ I have a plan for success.
✔ I am prepared to operate and grow this business responsibly.
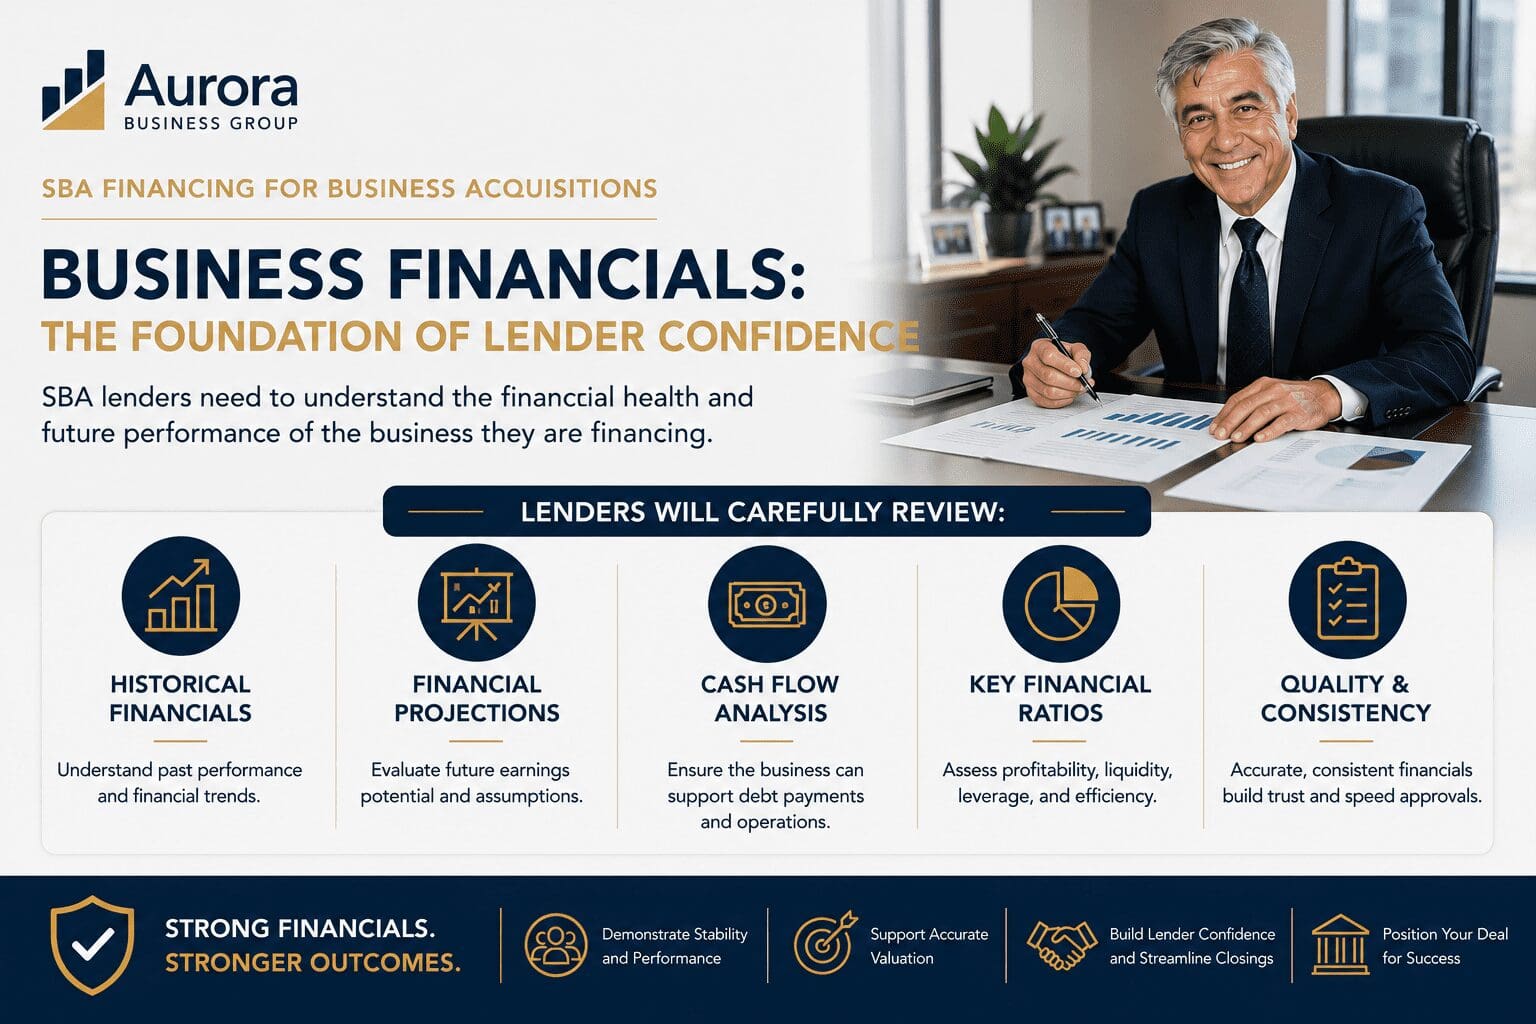
At Aurora Business Group, we help buyers organize lender-ready financing packages, identify potential underwriting concerns before they become obstacles, and position acquisitions for successful SBA approvals and closings.
Strong borrowers create lender confidence. Strong lender confidence creates stronger outcomes.
If you’re considering acquiring a business, what aspect of SBA financing do you find most challenging: borrower qualifications, financial documentation, valuation, or lender negotiations?
#SBALoan #BusinessAcquisition #EntrepreneurshipThroughAcquisition #ETA #SearchFund #BusinessFinance #SmallBusinessOwnership #MergersAndAcquisitions #BusinessBroker #AuroraBusinessGroup #BusinessGrowth #AcquisitionEntrepreneur