Many buyers believe the lender is primarily evaluating the business they want to acquire.
In reality, lenders are evaluating whether the business can generate sufficient cash flow to support the acquisition debt while continuing to operate successfully after closing.
That is why Business Financial Documentation is one of the most important components of any SBA financing package.
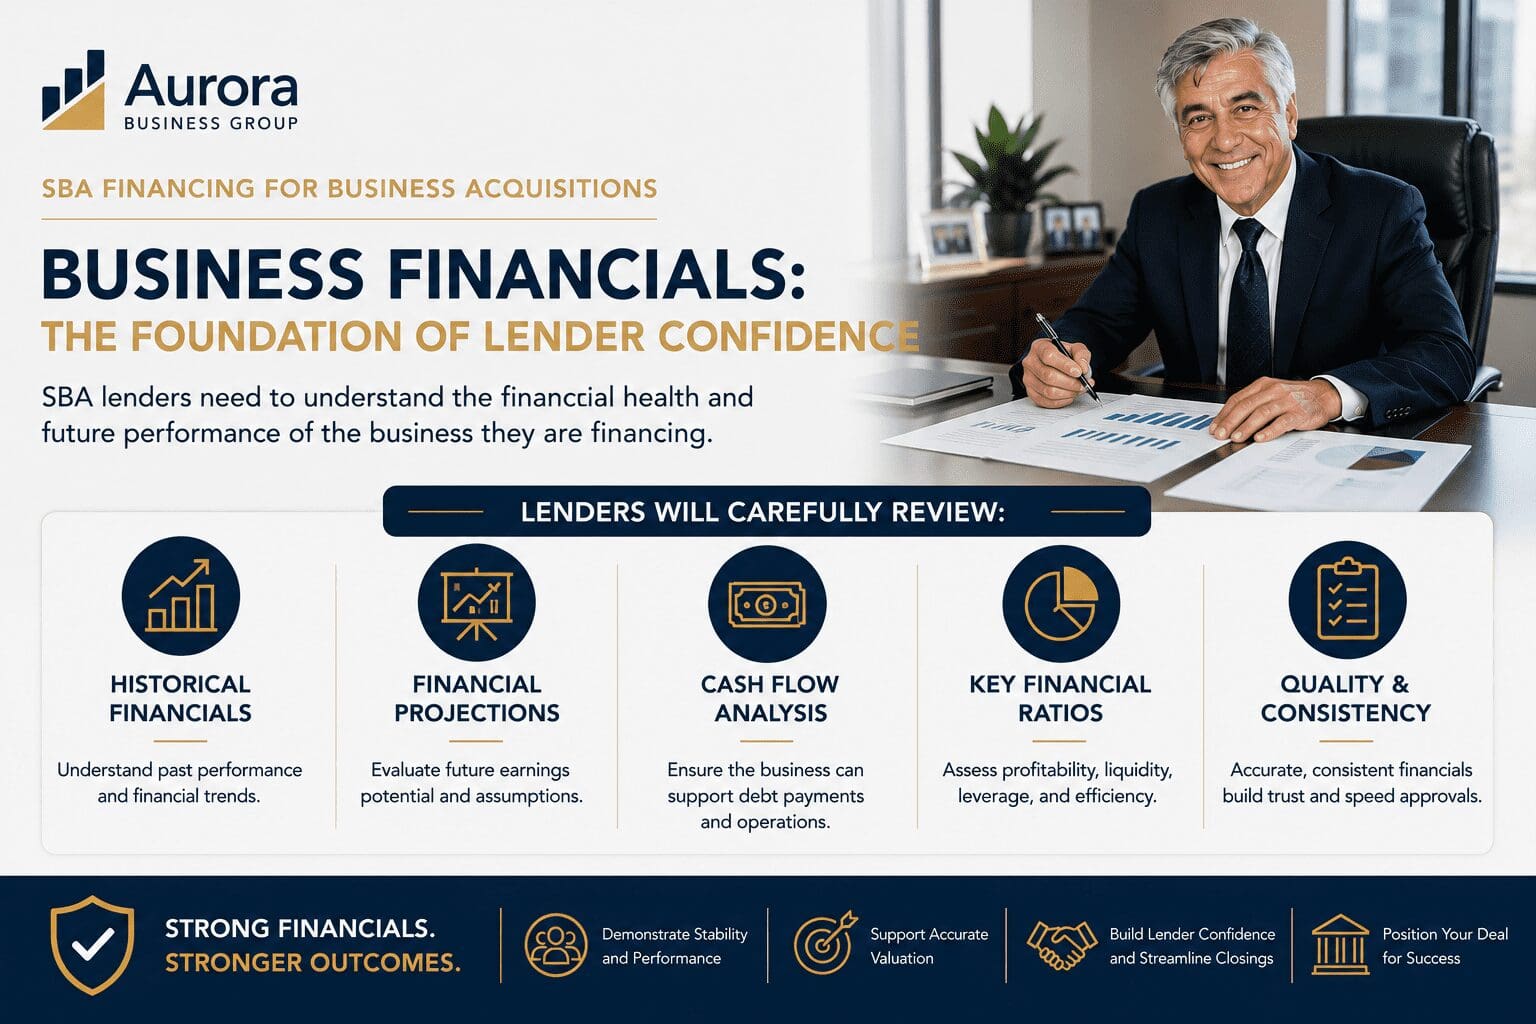
Before approving a loan, lenders typically conduct a detailed review of the company’s financial history, future projections, and post-closing liquidity position.
📈 Historical Financial Performance
Lenders want to understand how the business has performed over time and whether that performance is sustainable.
Key documents typically include:
✔ Last three years of business tax returns
✔ Profit & Loss Statements
✔ Balance Sheets
✔ Cash Flow Statements
✔ Current interim financial statements
These documents help lenders identify trends in revenue, profitability, customer concentration, margins, and operating efficiency.
Strong historical performance builds confidence. Inconsistent financial results often trigger additional questions and underwriting scrutiny.
🔮 Financial Projections Matter
Past performance is important, but lenders are financing the future.
That is why SBA lenders typically require financial projections covering the next 12 to 36 months.
These projections should include:
✔ Revenue forecasts
✔ Expense assumptions
✔ Cash flow projections
✔ Debt service coverage analysis
✔ Growth and hiring assumptions
The goal is not to predict the future perfectly. The goal is to demonstrate that management understands the business, has a realistic operating plan, and can support the new debt obligations.
💵 Cash Flow Is King
One of the most important questions every lender asks is:
“Can this business comfortably make the loan payments?”
Lenders perform a detailed cash flow analysis to determine whether the company generates enough earnings to cover:
- Loan payments
• Payroll
• Vendor obligations
• Taxes
• Ongoing operating expenses
Even highly profitable businesses can face financing challenges if cash flow is inconsistent or insufficient.
📋 Working Capital Planning
A successful acquisition requires more than simply closing the transaction.
Buyers must also demonstrate they have sufficient liquidity to operate the business after closing.
Lenders often review:
✔ Sources and Uses of Funds
✔ Working capital requirements
✔ Inventory needs
✔ Accounts receivable cycles
✔ Post-closing liquidity plans
Businesses that are undercapitalized after closing often struggle, regardless of how strong the acquisition opportunity may appear.
🎯 What Strong Buyers Understand
The strongest acquisition candidates recognize that SBA financing is not simply about obtaining a loan.
It is about demonstrating:
- Financial discipline
• Sound planning
• Realistic projections
• Sustainable cash flow
• Long-term operational success
When buyers present clear, organized financial information, lenders gain confidence in both the business and the management team.
At Aurora Business Group, we help buyers prepare lender-ready financing packages, analyze cash flow, organize financial documentation, and position acquisitions for successful SBA approvals and closings.
Strong financials create lender confidence. Strong lender confidence creates stronger outcomes.
What financial challenge has been the most difficult part of evaluating a business acquisition opportunity?
#SBALoan #BusinessAcquisition #BusinessFinance #EntrepreneurshipThroughAcquisition #ETA #SearchFund #SmallBusinessOwnership #BusinessBroker #MergersAndAcquisitions #AuroraBusinessGroup #BusinessGrowth #FinancialAnalysis